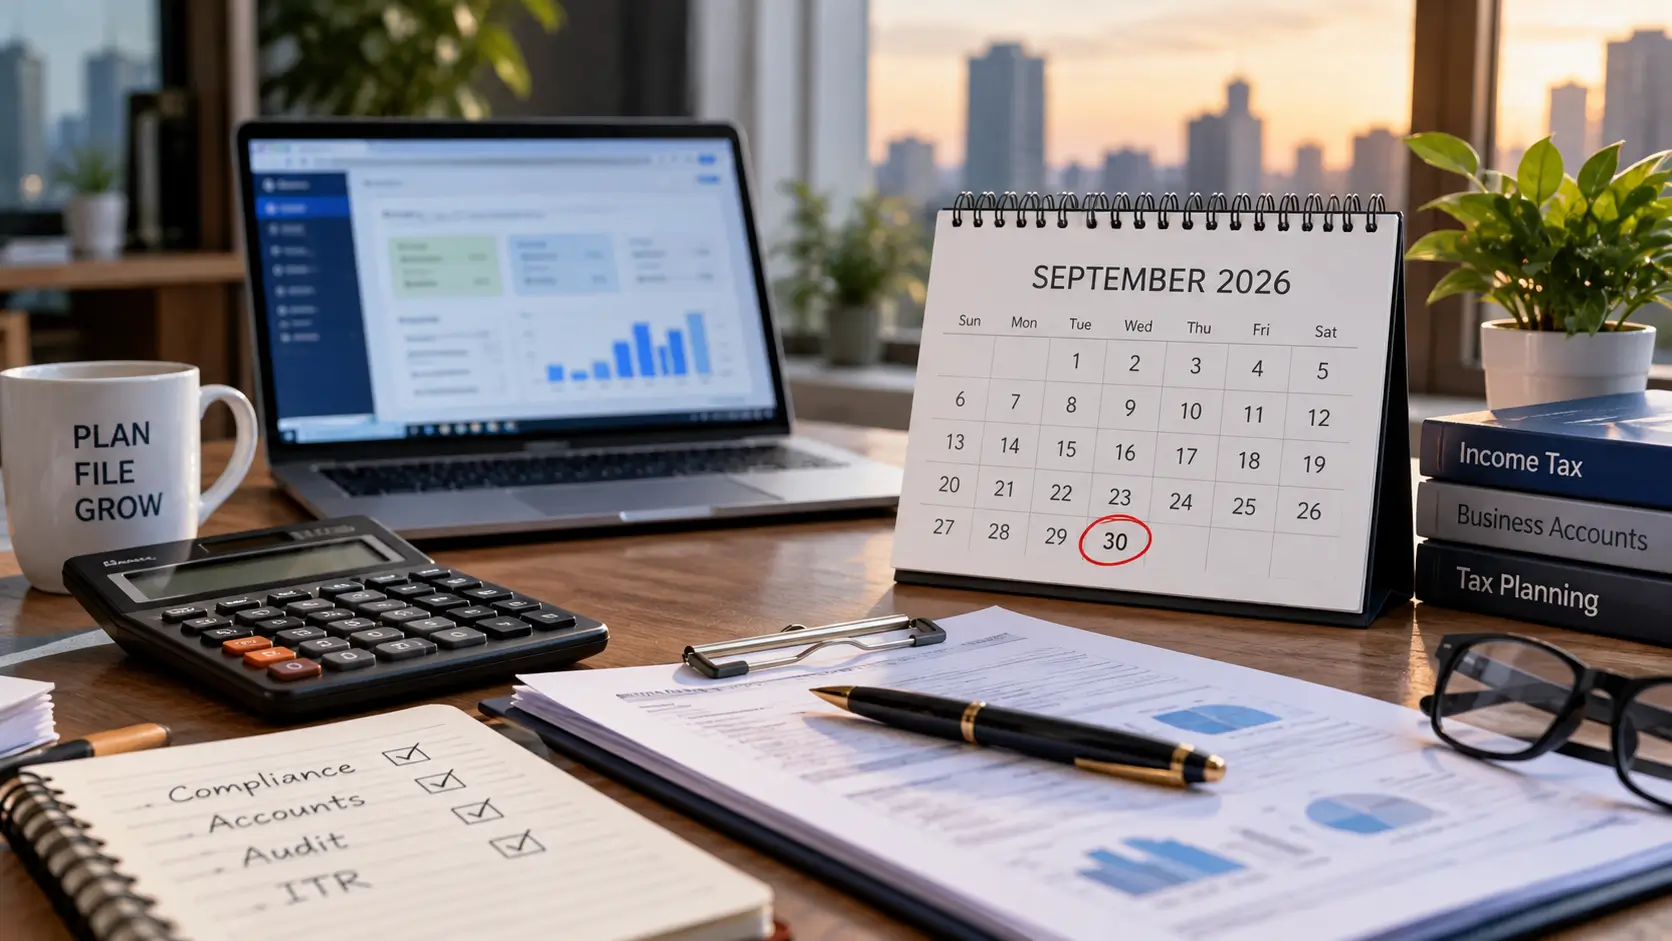
The income tax audit deadline for AY 2026-27 has not been officially extended as of September 16, 2026, based on the latest official Income Tax Department information reviewed for this article. The current deadline for furnishing the tax-audit report for FY 2025-26 remains September 30, 2026.
At the same time, several professional associations have requested that the government extend the deadline to October 31, 2026. Their representations cite the compressed compliance calendar, staggered availability of ITR utilities, additional reporting requirements and the amount of reconciliation involved in completing tax audits.
This distinction is important: a request for an extension does not mean that CBDT has granted one.
For now, taxpayers covered by tax-audit requirements should proceed on the basis that September 30 remains the applicable deadline unless the Central Board of Direct Taxes issues a formal extension.
Quick answer: Has the tax audit deadline been extended?
No official extension has been announced in the sources reviewed as of September 16, 2026.
The Income Tax Department’s current guidance states that the tax-audit report for FY 2025-26, corresponding to AY 2026-27, is due on September 30, 2026.
Professional bodies are asking for the deadline to be moved to October 31, but the requested extension is not the same as an approved extension.
Therefore, taxpayers should not assume that they automatically have until October 31.
What is the current tax audit deadline for AY 2026-27?
For taxpayers whose accounts are subject to tax audit for FY 2025-26, the current tax-audit report deadline is:
September 30, 2026
The Income Tax Department says that the FY 2025-26 audit remains under the Income-tax Act, 1961 and uses the existing tax-audit forms applicable under that law.
The relevant forms include:
- Form 3CA
- Form 3CB
- Form 3CD
The Chartered Accountant files the report electronically, after which the taxpayer must approve the report through the income-tax e-filing account.
Why are Chartered Accountants asking for an extension?
Several professional associations have submitted representations seeking additional time.
The requests are not based on a single issue. The associations have pointed to a combination of compliance pressures during August and September.
One issue is the revised compliance calendar. The deadline for business taxpayers who are not subject to tax audit was set at August 31, 2026. Tax-audit reports are then due on September 30.
Professional bodies argue that this leaves a relatively compressed period for completing audit work after accounts, reconciliations and other tax information are prepared.
Associations have also pointed to the staggered availability and subsequent updating of ITR utilities for audit-related taxpayers.
Another issue is the volume of information that Chartered Accountants need to reconcile and verify, including books, financial statements, GST information, TDS/TCS records and information available through the tax department’s systems.
Who has requested the tax audit deadline extension?
The request for additional time is not coming from just one organisation.
The Chandigarh Chartered Accountants Taxation Association submitted a representation dated September 14, 2026 requesting that the tax-audit deadline be moved from September 30 to October 31.
The Punjab Accountants Association submitted a similar representation dated September 11, requesting an extension to October 31.
The Tax Bar Association, Bhilwara also submitted a representation on September 14 seeking an extension for tax-audit reports and related forms.
On September 16, the Maharshi Bharadwaj Chartered Accountants’ Association, Prayagraj submitted another representation seeking a one-month extension.
The common request is therefore becoming clear: professional bodies want the tax-audit deadline moved to October 31, 2026.
However, these are representations to the government. They do not themselves change the statutory deadline.
What are the important income-tax deadlines?
For AY 2026-27, the compliance calendar includes several different dates.
| Requirement | Current deadline |
|---|---|
| Business/profession taxpayers not requiring audit | August 31, 2026 |
| Tax Audit Report | September 30, 2026 |
| Audit-case ITR, generally | October 31, 2026 |
| Transfer-pricing audit report | October 31, 2026 |
| ITR for transfer-pricing cases | November 30, 2026 |
This distinction is important because the tax-audit report and the income-tax return are separate compliance steps.
A taxpayer who is subject to tax audit generally needs the audit report completed before the corresponding return can be filed.
Which forms are used for the FY 2025-26 tax audit?
The transition to the Income-tax Act, 2025 can cause confusion because the law and forms change for later tax years.
For FY 2025-26 / AY 2026-27, the Income Tax Department says taxpayers should continue using the forms prescribed under the Income-tax Act, 1961.
That means the tax-audit reporting structure includes:
- Form 3CA where accounts are audited under another law;
- Form 3CB for other cases requiring tax audit; and
- Form 3CD for the statement of particulars.
The new unified Form 26 belongs to the tax-audit framework for Tax Year 2026-27, whose report deadline is September 30, 2027.
This transition-year distinction is important because using the new form for the wrong year would create unnecessary confusion.
Who generally needs a tax audit?
Tax audit requirements depend on the nature of the taxpayer’s business or profession and the applicable thresholds and presumptive-tax rules.
The Income Tax Department’s current guidance states that the tax-audit thresholds for the relevant framework include:
- business turnover or gross receipts exceeding ₹1 crore, subject to the higher ₹10 crore threshold where the prescribed cash-transaction conditions are satisfied;
- professional gross receipts exceeding ₹50 lakh; and
- certain taxpayers who opt out of presumptive taxation and fall within the specified conditions.
Taxpayers should determine applicability based on their individual facts rather than relying only on turnover.
A Chartered Accountant should be consulted where the tax-audit requirement is unclear.
What happens if the tax audit deadline is missed?
For FY 2025-26 / AY 2026-27, failure to get accounts audited or furnish the required audit report can attract a penalty under Section 271B.
The statutory penalty is generally the lower of:
- 0.5% of total sales, turnover or gross receipts, as applicable; or
- ₹1.5 lakh.
However, this does not mean that every late audit automatically results in the maximum penalty.
Section 273B provides that certain penalties, including Section 271B, may not be imposed where the taxpayer proves that there was a reasonable cause for the failure.
That provision should not be interpreted as permission to ignore the deadline. Taxpayers should maintain evidence supporting any genuine reason for delay and obtain professional advice about their particular circumstances.
Has CBDT extended the deadline to October 31?
Not as of September 16, 2026, based on the official material reviewed.
This is the most important point for readers searching for an “income tax audit date extension.”
Several associations have requested October 31, but the Income Tax Department’s current published guidance continues to state September 30.
The practical rule is therefore simple:
Until CBDT formally announces an extension, treat September 30, 2026 as the tax-audit deadline.
A government notification, circular or official Income Tax Department update would be required to change the applicable deadline.
Why taxpayers should not wait for an extension announcement
Taxpayers and Chartered Accountants who are already preparing their audit reports should continue working toward the existing deadline.
Waiting for a possible extension creates an unnecessary compliance risk.
If an extension is subsequently announced, taxpayers may gain additional time. If no extension is announced, however, work delayed while waiting could leave too little time for reconciliation, review, digital filing and taxpayer approval.
The safer compliance approach is therefore to work toward the currently notified date.
What should taxpayers do now?
If your accounts are subject to tax audit, check the following:
- Confirm that tax audit is actually applicable to you.
- Complete the books and financial statements.
- Reconcile turnover and GST records.
- Reconcile TDS/TCS information.
- Check AIS, TIS and Form 26AS data.
- Provide the required documents to your Chartered Accountant.
- Review Form 3CD disclosures carefully.
- Ensure the audit report is uploaded electronically.
- Approve the report through your e-filing account after the CA files it.
- Do not assume an extension exists until CBDT officially announces one.
The taxpayer’s approval step is also important. Uploading the audit report by the Chartered Accountant is not necessarily the end of the compliance process.
What if CBDT announces an extension later?
If CBDT issues a formal notification extending the deadline, the article should be updated immediately with:
- the notification date;
- the new tax-audit deadline;
- the affected taxpayers;
- affected forms;
- whether the corresponding ITR deadline also changes;
- any separate rules for transfer-pricing cases.
Until that happens, the September 30 deadline remains the operative date.
Bottom line
The income tax audit deadline for AY 2026-27 has not been officially extended as of September 16, 2026 based on the current official information reviewed.
The existing tax-audit deadline is September 30, 2026.
Several professional associations, including bodies representing Chartered Accountants in Chandigarh, Punjab, Bhilwara and Prayagraj, have requested that the deadline be extended to October 31, 2026.
That request is significant because it shows that professional bodies are seeking additional compliance time, but it should not be confused with an actual government extension.
For now, taxpayers subject to audit should continue preparing for September 30, 2026 and wait for a formal CBDT notification before treating any later date as official.
FAQ
Has the income tax audit deadline been extended for 2026?
No official extension has been identified as of September 16, 2026. The current tax-audit deadline for AY 2026-27 remains September 30, 2026.
Is the tax audit deadline extended to October 31, 2026?
Not currently. Several professional associations have requested October 31, but a request is not an approved CBDT extension.
What is the tax audit deadline for AY 2026-27?
The current tax-audit deadline is September 30, 2026.
What is the ITR deadline for audit cases?
For audit cases other than transfer-pricing cases, the current ITR deadline is generally October 31, 2026. Transfer-pricing cases have a November 30, 2026 ITR deadline.
Why are CAs asking for an extension?
Professional associations cite compressed compliance timelines, staggered ITR utility releases and updates, overlapping statutory work and additional reconciliation and reporting requirements.
Which forms are used for the AY 2026-27 tax audit?
For FY 2025-26 / AY 2026-27, the applicable tax-audit reporting uses Forms 3CA or 3CB along with Form 3CD, depending on the case.
What is the penalty for missing the tax-audit deadline?
Under Section 271B, the penalty can be the lower of 0.5% of sales, turnover or gross receipts, as applicable, or ₹1.5 lakh. Section 273B provides relief where the taxpayer can establish reasonable cause for certain failures.
Should taxpayers wait for a possible extension?
No. Unless CBDT formally announces an extension, taxpayers should proceed on the basis that September 30, 2026 remains the applicable deadline.
DISCLAIMER
Tax disclaimer:
This article provides general information about the AY 2026-27 tax-audit deadline and reported extension requests. Tax obligations and penalties can depend on individual circumstances. Verify the latest CBDT/Income Tax Department notification and consult a qualified tax professional for advice specific to your case.